
The IPO Volatility
CoreWeave shares surged 42% on Tuesday, closed at $52.57, and resulted in a market capitalization of nearly $25 billion. This recovery follows a Monday decline where shares dropped 10% below the initial $40 IPO price. The company priced its March 2025 offering at $40, which sat below the expected $47 to $55 range. While many outlets reported a $19 billion valuation at pricing, the fully-diluted count including options and restricted stock reached $23 billion. Nvidia anchored the $1.5 billion raise with a $250 million order. The stock opened at $39 on Friday and marked the largest venture-backed tech IPO for a US company since 2021. If you follow the volatility, remember that the $40 price signaled soft institutional demand during the roadshow. The company issued 37.5 million Class A shares and reported that Microsoft accounted for 62% of its 2024 revenue. CoreWeave also maintains contracts exceeding $15 billion that it has yet to fulfill. CoreWeave’s revenue grew more than 737% last year to $1.92 billion. CEO Michael Intrator indicated that third-quarter operating profit will reach $160-190 million.
Scale and Performance
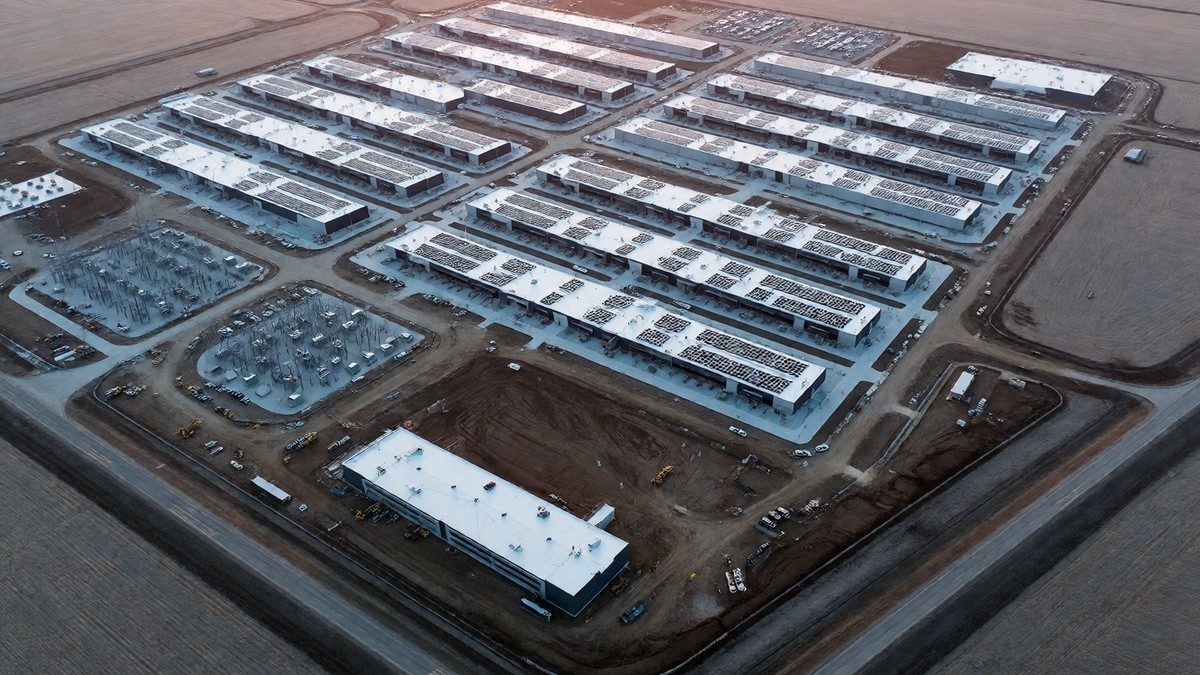
CoreWeave secures massive revenue through long-term hardware commitments. An $11.9 billion five-year contract with OpenAI supports the global distribution of ChatGPT models to millions of users, while an expanded agreement with Meta targets $21 billion in capacity through 2032. This Meta agreement requires the deployment of approximately $260 million of GPU capacity every month. OpenAI will also invest $350 million in CoreWeave stock through a transaction separate from the IPO. These contracts involve the deployment of NVIDIA H200 and Blackwell systems across 32 data centers. The NVIDIA H200 platform provides 4.8 TB/s memory bandwidth and 141 GB of HBM3e GPU memory capacity, which delivers up to 1.9X higher performance than H100 GPUs. These instances can be deployed in clusters with up to 42,000 GPUs. The company’s 32 sites housed over 250,000 Nvidia GPUs by the end of 2024. CoreWeave has $104 billion in contracted revenue backlog as of the end of June. Since the start of 2024, CoreWeave has set up nine new data centers and has 11 more in progress. CoreWeave operates 51 data centers across North America and Europe with 1.5 GW of active power.
| Instance Type | On-Demand Price (per GPU) |
|---|---|
| 8x H100 Node | $49.24 |
| 8x B200 Node | $68.80 |
| GH200 (Single GPU) | $6.50 |
| 8x L40 Node | $10.00 |
Risk and Competition
CoreWeave faces staggering financial obligations. Total indebtedness reached $35.6 billion as of June 30, 2026. This debt load follows a 2024 net loss of $863.4 million despite a 700% revenue surge to $1.92 billion. CoreWeave carries $35.6 billion in total indebtedness as of June 30, 2026, which reflects the immense capital requirements involved in building massive, high-performance data centers for AI workloads across North America and Europe to satisfy its growing global customer base. The company is raising capital through a $3.55 billion global debt offering, which includes $2 billion in euro notes and $1.25 billion in dollar notes. The company’s net interest expense rose to $1,229 million, as it relies on multiple funding channels that include $6.6 billion in convertible notes and $3.1 billion in leveraged loans. The company manages a high concentration of risk, as 77% of its 2024 revenue came from just two clients, Microsoft and Nvidia. Microsoft and Amazon develop custom silicon to challenge the Nvidia-centric model CoreWeave uses, meaning the company’s expansion relies entirely on the continued appetite for Nvidia hardware. Will the company maintain its gross margins as the hardware cycle accelerates?